

In short. You can file a summary suit only when you're claiming a fixed sum of money, a debt or liquidated demand, that arises on one of the sources Order 37 Rule 1 CPC lists. That means a written contract, a guarantee, an enactment, a cheque, bill of exchange, hundi or promissory note, or receivables assigned to you. Below are seven ordinary business situations that qualify, and the claims that don't. Checking your own papers takes about an hour. If the claim fits, the suit can usually be ready within weeks.
Is this your situation?
- You delivered goods against a signed purchase order. The buyer used them, and three months on you haven't seen a rupee.
- Your client approved the work by email, then went silent the week the fixed fee fell due.
- A tenant cleared out of your shop overnight, leaving months of rent unpaid under a written lease.
- You lent money to another business, and there's a loan letter, a pronote, or at least an email where they admit it.
- A cheque came back from the bank marked 'funds insufficient'. Or a director signed a personal guarantee and now won't pick up.
- A friend says it's a damages claim. Your accountant says it's a plain debt. You'd like to know which.
The quick answer, before the detail
Three boxes need ticking. Money is the only thing you want from the court. The sum is already known, or a calculator and the documents will get you there, so the judge has nothing to assess. And the claim grows out of one of the sources listed in Order XXXVII Rule 1(2) of the Code of Civil Procedure, 1908. That list is short. Hundis, promissory notes and bills of exchange. Written contracts. A statute that fixes the amount. Written guarantees. Receivables someone has assigned to you.
Miss any one of them and the summary route is shut. The claim then goes as an ordinary suit. That isn't a disaster. Even an ordinary commercial suit can end early, through summary judgment under Order XIIIA. But the defendant gets to file a written statement as of right, instead of having to ask the court for leave to defend, and that need to ask is the whole point of a summary suit. Why it matters so much is explained on our page on summary suits for quicker recovery. This guide deals with the question before that one. Does your claim qualify at all?
What Order 37 Rule 1 actually says
Order XXXVII Rule 1(1), CPC: the courts
The Order applies to High Courts, City Civil Courts and Courts of Small Causes, and to any other court the High Court notifies. The High Court can also restrict it to certain categories of suits. Commercial courts across Delhi and the NCR hear summary suits all the time. Filing somewhere unfamiliar? Confirm first that the court has Order XXXVII jurisdiction.
Order XXXVII Rule 1(2)(a): negotiable instruments
This covers hundis, pronotes and bills of exchange. Since a cheque is simply a bill of exchange drawn on a bank, a claim on a bounced cheque falls in this clause.
Order XXXVII Rule 1(2)(b): debts and liquidated demands
This is the clause most business claims use. The plaintiff must want nothing but money the defendant owes, as a debt or liquidated demand, interest included or not. And that money must come from one of four places. A written contract is the first. Second, a statute fixing the sum as a debt, not as a penalty. Third, a guarantee, though only where what the main debtor owes is itself a debt or liquidated demand. Fourth, receivables that were assigned to the person now suing. The Factoring Regulation Act, 2011 added that fourth one.
Order XXXVII Rule 2(1): nothing else in the plaint
The plaint has to state that it claims no relief outside Rule 1. So qualifying isn't only about your documents. It's about what you ask for, too.
The conditions every claim has to meet
Read the rules side by side and four summary suit conditions fall out. First, you want money. Not an injunction. Not a declaration, possession or accounts. Second, what you want is a debt or liquidated demand. A debt is money already owing, the price of goods you've delivered, say. A liquidated demand is a figure the parties agreed, or one you can calculate exactly from the contract: 500 cartons at the agreed rate, eleven months of rent, interest at the rate in the deed. Third, the claim has to come from a listed source. Fourth, Order XXXVII must apply in the court where you file.
Then there are two hurdles every money suit faces anyway. One is time. A business debt usually gives you three years under the Limitation Act, 1963 from the day payment was due, and the clock starts afresh with a written acknowledgment (Section 18) or a part payment (Section 19). Our guide on limitation for a summary suit walks through the counting. The other is value. A commercial dispute worth Rs 3 lakh or more makes this a commercial suit, and that normally puts Section 12A pre-institution mediation ahead of filing.
The word that trips people up is 'written'. A written contract doesn't have to be one signed document headed 'Agreement'. A purchase order accepted by email can be one. So can a quotation the buyer signed and sent back, or a run of letters that settles price and quantity. What won't do is a purely oral deal, backed later only by bank entries.
The 7 qualifying situations, at a glance
- 1. The price of goods under a written contract or purchase order. The bread-and-butter summary suit for manufacturers, traders and distributors.
- 2. A fixed fee for services or work under a signed contract. It works where the fee was agreed up front and the client accepted the work.
- 3. Rent and charges under a written commercial lease. Arrears of fixed rent qualify. A claim for damage to the premises doesn't.
- 4. Money lent under a written loan agreement or acknowledgment. A business loan someone put in writing, with a fixed repayment.
- 5. Bounced cheques, promissory notes, bills of exchange and hundis. Here the instrument itself is what you sue on.
- 6. A written guarantee. That includes a director personally guaranteeing the company's dues.
- 7. Receivables assigned to you. Invoices a factor has bought, say, or a debt someone assigned to you in writing.
Situation 1: You supplied goods and the buyer hasn't paid
This is the summary suit we see most often in Delhi NCR. A manufacturer or trader supplies goods against a supply agreement or a purchase order, raises invoices, and the buyer stops paying. The rate per unit is fixed. The quantity is on the delivery challans. Working out what's due is simple arithmetic, which makes it a liquidated demand arising on a written contract.
Whether it holds up depends on proving two things: the buyer agreed the terms in writing, and the goods reached it. Put a signed purchase order or supply agreement together with challans or goods receipt notes signed at the buyer's end, e-way bills and the buyer's own TDS deductions, and you've got a strong file. With no purchase order and only invoices, it's less certain, and it turns on what else shows acceptance. Our guide on summary suits on invoices goes into that properly.
The defence will usually be quality, short supply or rate. If someone did complain at delivery, deal with it openly in the plaint and show how it was settled, with a credit note for instance. A complaint that shows up for the first time after your legal notice counts for far less at the leave stage.
Situation 2: Your fee was fixed, the work was done, the money wasn't paid
Service firms can use it as well. They have one extra thing to prove. Picture a software house in Gurugram whose signed SOW puts Rs 9 lakh on each milestone, and whose client signed off every milestone by email. Fixed sum, written contract. It fits. Compare a consultant who did 'whatever was needed', with the rate to be agreed later. A judge would have to put a value on that work, so it doesn't fit.
Acceptance of the work is the soft spot. Clients often pay the first milestone, go quiet on the second, and then discover the deliverable was defective. Advocate B.K. Singh tells service businesses to treat every acceptance email, UAT sign-off, completion certificate or handover note as a payment document, and to file it away the day it lands. At the leave to defend stage, that one page often decides whether the client's 'deficient work' story looks real or made up.
Construction and interior contracts work much the same way. Certified running bills under a written contract are a liquidated demand. Extra work that nobody measured or certified usually isn't. That claim belongs in an ordinary suit, or under the arbitration clause if the contract has one.
Situation 3: The tenant owes rent on a shop, office or godown
Rent owed on a shop, an office, a godown or a factory shed under a written lease is a debt on a written contract. Where the place was let purely for trade or commerce, Section 2(1)(c) of the Commercial Courts Act, 2015 makes the dispute commercial. Cross Rs 3 lakh and you're in the Commercial Court. If the lease fixes maintenance charges and yearly escalation, those can be added too.
There are two limits. You can't join eviction, possession or mesne profits (compensation for use and occupation after the lease ended) to the rent claim in a summary suit, because those reliefs sit outside Order XXXVII. And damage to the premises, or rent lost while a shop stood empty, is a damages claim. It's not a liquidated demand. If the tenant has already gone and only the rent is in dispute, a summary suit is often the cleanest way. Where more is at stake, our page on shop and office lease disputes covers the wider options.
Situation 4: You lent money and have it in writing
Across Delhi NCR, businesses lend to each other all the time: inter-corporate deposits, a trader helping a trader, a quick advance to a supplier. Most of it is done on trust and a phone call. For a summary suit you need paper. A loan agreement works. So does a pronote, a written admission of the debt, or a letter or email where the borrower confirms the sum and the repayment terms. The bank transfer shows the money moved. The writing shows it was a loan, repayable on fixed terms.
A loan with nothing in writing at all, and only WhatsApp messages asking for more time, is harder. Messages that plainly admit the amount can sometimes work as a written acknowledgment, but judges read them closely. The two ends of this range are covered in our guides on summary suits on a promissory note or loan agreement and getting back money lent with no written agreement.
Situation 5: A cheque bounced, or you hold a pronote, bill or hundi
Suits on negotiable instruments are the oldest category in Order XXXVII, and the simplest. The instrument is already a written promise to pay a fixed sum. A bounced cheque with the bank's return memo can found a summary suit even if nothing else about the deal was written down. You're suing on the cheque. The same goes for a promissory note, a hundi or an accepted bill of exchange.
A bounced cheque also opens the criminal route under Section 138 of the Negotiable Instruments Act, 1881. That route has its own strict 30-day notice and complaint deadlines, and you can read about them on chequebouncelawyer.com. The civil suit and the criminal complaint can run side by side. How they fit together is explained in our guide on a summary suit on a bounced cheque.
Situation 6: Someone signed a guarantee, maybe the director himself
Distributors, landlords and lenders in the NCR often get a company's director, or a group company, to sign a guarantee. Order XXXVII Rule 1(2)(b)(iii) allows a summary suit on it, but only where the claim against the principal debtor is itself a debt or liquidated demand. A guarantee of 'all sums due under the distribution agreement' will carry a summary suit for unpaid invoices. It won't carry the distributor's claim for lost profits.
Under Section 128 of the Indian Contract Act, 1872, the guarantor's liability is co-extensive with the principal debtor's unless the guarantee says otherwise. You can sue the company and the guarantor together in one summary suit. Read the guarantee for conditions first. Some require a written demand on the guarantor before you sue, and you'll need to comply before filing. This is also one of the few ways a director ends up personally liable for a private limited company's dues. Otherwise that's rare.
Situation 7: You bought or were assigned someone else's receivables
Since the Factoring Regulation Act, 2011, Order XXXVII has covered suits by an assignee to recover receivables. A factoring company or NBFC that bought a supplier's invoices can sue the buyer summarily. So can a business that took a written assignment of a debt, for example when it bought another business.
The assignee needs the assignment deed, proof that the debtor was told about the assignment, and the underlying papers that would have backed the original creditor's claim. Any defence the debtor had against the original creditor can be raised against the assignee too. So the quality of those old invoices and delivery proofs still counts.
When a summary suit isn't available
Damages are out. So is lost profit, compensation for delay, or any figure the judge has to work out. People are often surprised that a liquidated damages clause doesn't help. Under Section 74 of the Indian Contract Act courts usually treat that number as an upper limit, and they still want the loss proved, so it isn't a debt. Partners fighting over accounts can't use it either. Nor can someone with a running account where the balance isn't known until accounts are taken, or anyone who wants an injunction, declaration or possession alongside the money. Those go as ordinary suits. Our page on breach of contract claims covers the damages side.
If a client brings Advocate B.K. Singh a claim that's part debt, part damages, his first worry is Order II Rule 2 of the CPC. Leave out a relief you could have asked for on the same cause of action, and you generally can't come back for it in a second suit. Suing summarily for the debt now and for damages on the same contract next year won't work, unless the court lets you omit that relief. It usually comes down to two choices. Drop the damages and keep the speed. Or claim everything in an ordinary suit. Which is right depends on how big the damages are, and how well you can prove them.
A summary suit against a government department or a PSU is possible. There are extra formalities, though, notice under Section 80 of the CPC among them. Our guide on summary suits against a government body explains them.
Does the Rs 3 lakh line decide whether you can file?
No. The line changes the forum and the paperwork, not your right to sue. Above it, in a commercial dispute, you have a commercial summary suit. That means the Commercial Court, Section 12A mediation unless you're asking for urgent interim relief, and the stricter commercial rules on statements of truth and on disclosing documents. How the value is counted is in our guide on the Rs 3 lakh specified value.
Smaller claims, under Rs 3 lakh, can still be filed under Order XXXVII. They go to the regular civil court that has jurisdiction, as long as that court is one where Order XXXVII runs. No Section 12A mediation for those. As for the upper end, Delhi's district commercial courts take suits up to Rs 2 crore and the Delhi High Court takes anything larger. In July 2026 it was recommended that the limit go up to Rs 10 crore. Check where it stands today.
All seven, compared
| Situation | Main document | Defence you'll usually hear | When the 3-year limitation usually starts |
|---|---|---|---|
| Price of goods | The PO or supply contract, signed, and the challans | Bad quality, short supply, wrong rate | When the agreed credit period ends (Article 15), or the delivery date if no credit period was agreed (Article 14) |
| Fixed fee for services or work | Signed contract or SOW, plus proof the work was accepted | The work was poor or never accepted | The date the contract made the fee payable. With no date fixed, the day the work was finished (Article 18) |
| Rent under a lease | Written lease, rent ledger | Premises unusable, or adjust it against the deposit | When each month's arrears fell due (Article 52) |
| Loan | Loan agreement, promissory note, acknowledgment | 'That money was an investment', or 'it was a gift' | Turns on the loan terms. Get this checked |
| Cheque, note, bill, hundi | The instrument and the return memo | The cheque was only security and nothing was owed | Usually from the due date or the dishonour. Check which Article applies |
| Guarantee | Signed guarantee deed | The guarantee was discharged, or its conditions weren't met | Often from when you demanded payment from the guarantor, but read the deed |
| Assigned receivables | Assignment deed, notice to the debtor | Whatever defence the debtor had against the original creditor | Same as the underlying debt |
If it qualifies: how long, and what it costs
| Stage | Usual time (ranges) | Main costs, not counting the lawyer's fee |
|---|---|---|
| Going through the papers, sending notice | 1 to 4 weeks | Courier and email |
| Section 12A mediation (commercial suits) | Up to 3 months, and 2 more if extended | A small fixed fee set by the 2018 Rules (check today's schedule) |
| Filing | 1 to 3 weeks once mediation ends | Court fee, ad valorem, per the state schedule (confirm the latest figure), plus process fee |
| Appearance, summons for judgment, leave | Several months. It varies a lot from court to court | Affidavits, certified copies |
| Decree or trial | If leave is refused, the decree follows quickly. If it's granted, expect years | Trial costs if it's contested |
Testing your own claim in 30 minutes
Write down exactly what you want
If it's anything other than 'Rs X with interest', a summary suit probably isn't the right vehicle. An injunction, possession or damages needs a different kind of suit.
Find the document the claim stands on
It could be a signed agreement, a PO, the lease, a loan letter, the cheque, a pronote, the guarantee or an assignment deed. Whichever it is, it goes on top of the pile.
Check the figure is fixed
You should be able to reach the amount by arithmetic from the document: units times rate, months times rent, principal plus agreed interest. If you'd need an expert or the court to assess it, it isn't liquidated.
Reconcile the account
Knock off credit notes, returns, part payments and TDS. Get the figure wrong and you've invited a triable issue.
Check limitation
Jot down the due date, plus the latest part payment or written admission. If the three years are almost gone, don't wait.
Check value and court
Is it a commercial dispute worth Rs 3 lakh or more? Then it's the Commercial Court, after Section 12A mediation. Territory you'll work out under Section 20 of the CPC.
Papers that can rescue a borderline claim
- A purchase order or work order the buyer signed, or sent from its official email ID
- A balance or ledger confirmation from the debtor's accounts team, even a two-line email
- Delivery challans, goods receipt notes or e-way bills showing the goods reached the debtor's premises
- For services, the acceptance or completion certificate, or the sign-off email
- Your Form 26AS, if it shows the debtor deducted TDS on your invoices
- Any email or letter where the debtor asks for time to pay a stated amount
- The guarantee deed, promissory note or assignment deed, the original if you still have it
- A certificate under Section 63 of the Bharatiya Sakshya Adhiniyam, 2023 covering the electronic records you rely on
Invented example: four unpaid accounts on one trader's desk
This is an invented example. Picture a steel trader in Sahibabad Industrial Area sitting with four overdue accounts, wanting to know which of them can go summarily. Account one: a Loni fabricator owes Rs 22 lakh for TMT bars. There were signed purchase orders, and every challan carries the fabricator's yard stamp. Yes. A liquidated demand on a written contract.
Account two: Rs 6 lakh lent to another trader, with a one-page letter he signed giving the date he'd repay. Also yes. Account three: an Indirapuram builder's cheque for Rs 4.5 lakh, bounced with 'funds insufficient'. The cheque alone is enough for a summary suit. If the notice deadline is still open, a Section 138 complaint can go in alongside.
Account four is different: Rs 15 lakh from a transporter whose late delivery lost the trader an order. That's damages. It doesn't qualify, and if the trader pursues it at all, it'll be an ordinary suit. The three that do qualify are each above Rs 3 lakh and commercial. So each needs Section 12A mediation in Ghaziabad and then filing in the court designated as the district's Commercial Court, unless the debtor is located, or the cause of action arose, somewhere else.
What to do this week
Run the 30-minute test on every unpaid account. Separate the claims that are fixed debts on written documents from the ones that are really about damages or accounts. For those that qualify, gather the papers on the checklist, and send a balance confirmation request if you haven't had one lately. What comes next is in our guide on filing a summary suit step by step, and our summary suit page explains how we handle these cases.
Would you like your papers checked against Order XXXVII before spending money on court fee? Or to know whether a recent judgment changes things for your kind of claim? Write to Advocate B.K. Singh's team through the contact page.
Frequently asked questions
Can I file a summary suit on an oral agreement?
Usually not. The exceptions are a claim on a negotiable instrument like a cheque or promissory note, or one where a later written acknowledgment records the debt and its terms. Order XXXVII needs the debt to arise on a written contract, a guarantee, an enactment or an instrument. An oral deal backed only by bank entries normally goes as an ordinary suit.
Can a summary suit include interest?
Yes. Order XXXVII covers a debt or liquidated demand with or without interest. Where the contract sets a rate, claim at that rate and show the working clearly. The court can also award interest during the suit and after the decree under Section 34 of the CPC.
Can my partnership firm or proprietorship concern file one?
Yes. A firm can sue in its own name, but check its registration. If it's unregistered, Section 69 of the Partnership Act, 1932 stops it suing outsiders on its contracts. A proprietor sues personally, described as trading under the business name. A company or LLP files through an authorised signatory, with a board or partners' resolution to back it.
Is a summary suit possible below Rs 3 lakh?
Yes. The claim has to qualify, and Order XXXVII has to apply in that civil court. Under Rs 3 lakh you aren't in commercial territory, so there's no Section 12A mediation and the case goes to the regular civil court. For court fee and everything else, the normal rules apply.
Does a summary suit still work if the debtor disputes the amount?
It can. At the leave stage the court asks whether the dispute is genuine and backed by facts, or raised just to buy time. A dispute that first surfaces after the legal notice, with no earlier complaint, often carries little weight. A real, documented dispute may get the defendant leave, sometimes on condition of a deposit.
Can the summary suit and a cheque bounce case run together?
Yes. The summary suit is a civil claim for the money. The Section 138 complaint is a criminal case for the dishonour. They're independent and can run at the same time. Just keep the criminal route's 30-day notice and one-month complaint deadlines in view.
Can a company based abroad sue summarily in Delhi?
Yes, if the claim qualifies and the Delhi court has territorial jurisdiction, for instance because the Indian buyer carries on business in Delhi. The foreign plaintiff may be asked for security for costs. Papers signed abroad may need notarisation and an apostille or consular attestation.
What if only part of my claim fits Order 37?
You can limit the summary suit to the part that fits. Think about Order II Rule 2 of the CPC first, though. It can bar a later suit for relief arising from the same cause of action that you left out. The alternative is one ordinary suit for everything. Make this call before filing. Not after.
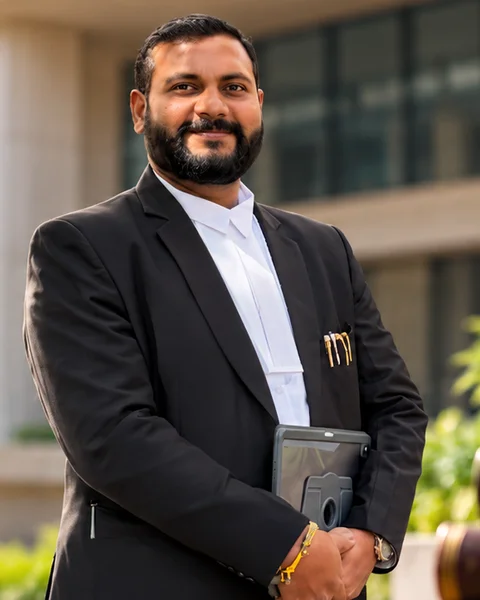
Advocate B.K. Singh
Founder of B.K. Singh & Associates. MCA, LL.B., LL.M. More than twenty years in practice before the Supreme Court, the Delhi High Court, district and commercial courts in Delhi NCR, and tribunals.
This guide explains the law in general terms and is not legal advice. For advice on your own papers, contact the team.